

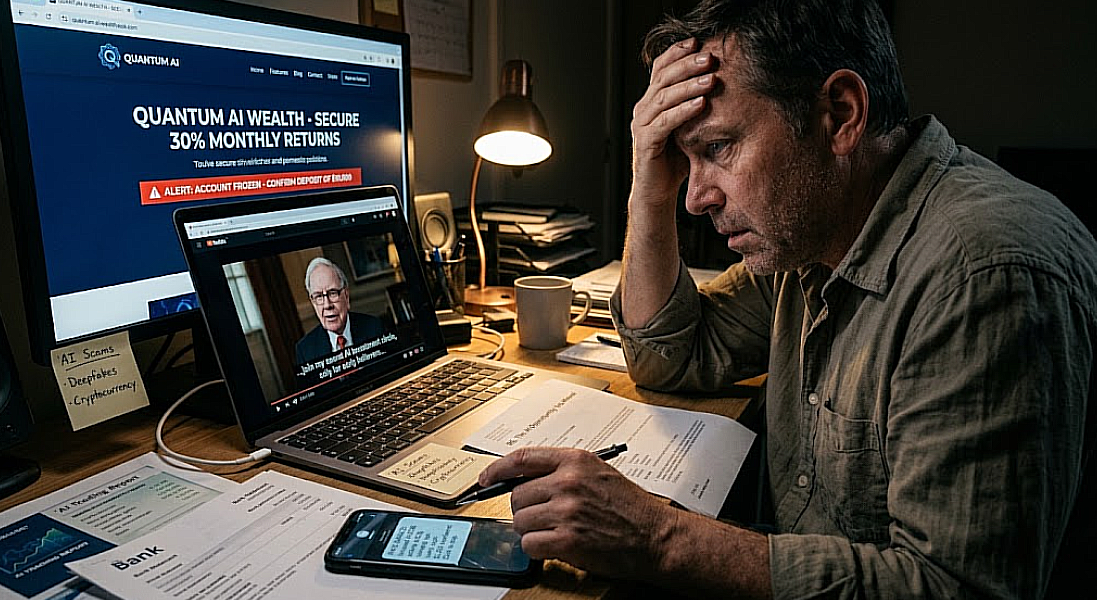
AI Financial Scams in 2026: Dangerous Warning Signs and Smart Ways to Protect Your Money
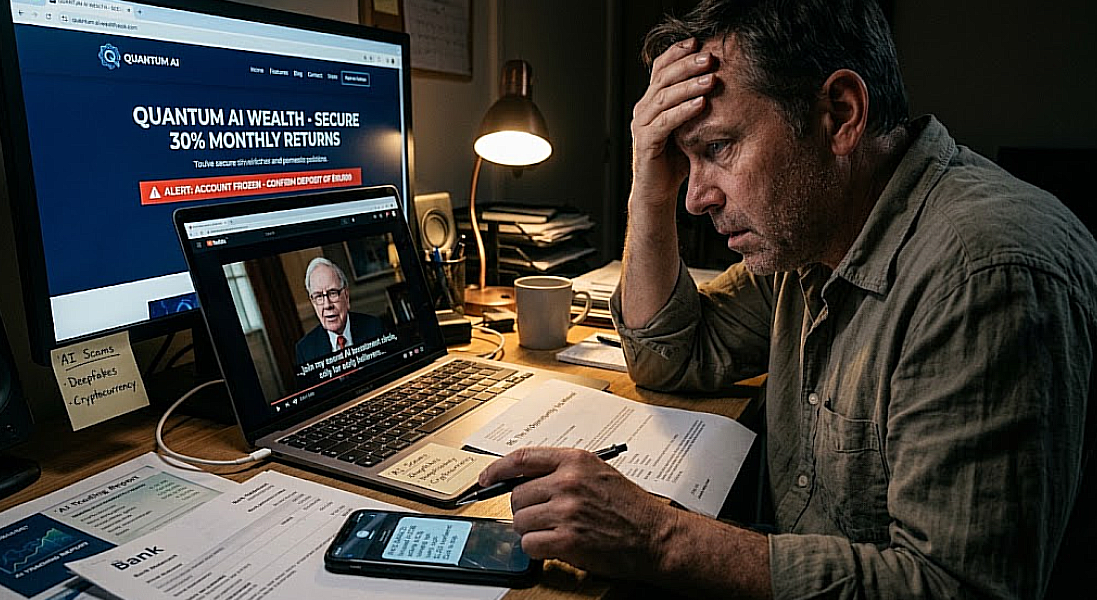
Artificial intelligence is changing how people manage money, research investments, and communicate online. Unfortunately, it is also giving financial criminals new ways to deceive consumers. Fraudsters can use AI-generated voices, realistic videos, convincing investment websites, and personalized messages to make fraudulent opportunities appear legitimate.
A scam that once relied on poorly written emails or suspicious-looking advertisements can now involve professional marketing, fabricated testimonials, and video clips that appear to feature trusted public figures. Some criminals even create fake investment communities where multiple accounts pretend to be successful investors encouraging newcomers to deposit money.
The financial consequences can be serious. According to the Federal Trade Commission (FTC), consumers reported losing more than $7.9 billion to investment scams in 2025, with a median individual loss exceeding $10,000. These figures concern investment scams broadly, not just scams involving artificial intelligence, but they demonstrate why investment fraud deserves serious attention.
For consumers, the challenge is no longer simply identifying bad spelling or an obviously suspicious email. It is learning how to verify financial claims, protect sensitive information, recognize manipulation, and respond quickly when something goes wrong.
This guide explains how AI financial scams work, which warning signs matter most, how to evaluate suspicious investment opportunities, and what to do if you believe your money or personal information has been compromised.
What Are AI Financial Scams?
AI financial scams are fraudulent schemes in which criminals use artificial intelligence to make deception more convincing, personalized, or efficient. The technology can help them generate messages, imitate voices, produce realistic images, create videos, and operate fraudulent websites.
AI is not inherently fraudulent. Banks, financial institutions, and legitimate businesses use AI for customer service, fraud detection, and other purposes. The danger arises when criminals misuse these capabilities to impersonate people, fabricate investment opportunities, or persuade consumers to transfer money.
The Federal Bureau of Investigation (FBI) has warned that generative AI can help criminals produce convincing content at scale, making financial fraud more difficult to recognize. The SEC and other investor-protection organizations have also warned about fraudulent platforms that claim to use sophisticated AI trading systems.
Common examples include:
- Deepfake investment promotions: Videos that falsely show a celebrity, business executive, or financial expert recommending an investment.
- AI voice-cloning scams: Calls or voice messages that imitate a relative, employer, adviser, or other trusted person.
- Fake AI trading platforms: Websites or applications that promise automated profits using supposedly advanced algorithms.
- Personalized investment messages: Messages generated to match a person's interests, financial goals, or recent online activity.
- Fake investment communities: Social media groups and messaging channels filled with fabricated success stories and coordinated recommendations.
- Impersonation of financial institutions: Messages designed to resemble communications from banks, brokers, regulators, or government agencies.
The technology can make these schemes look credible, but the underlying objective remains the same: persuade someone to surrender money, reveal confidential information, or provide access to a financial account.
How AI Is Making Financial Fraud More Convincing
Understanding the methods criminals use can help consumers recognize suspicious activity before it becomes expensive.
1. Deepfake Videos and Fake Celebrity Endorsements
A fraudulent investment advertisement might show a familiar public figure discussing an exciting opportunity. The video may appear polished, and the speaker's facial expressions and voice may seem realistic.
However, the person may never have endorsed the investment. Criminals can manipulate existing footage or generate synthetic content to create the impression of an authentic recommendation.
These promotions may claim that an individual has discovered a profitable trading method, invested in a particular cryptocurrency, or partnered with a company offering unusually high returns.
The most important lesson is that a recognizable face is not proof of legitimacy. Search for the endorsement through the person's verified channels and the company's independently verified website. Do not rely on the advertisement's own links or contact information.
2. Voice Cloning and Emergency Payment Requests
AI voice-cloning tools can imitate a person's speech using audio samples. Criminals may use publicly available recordings or other material to create a voice message that sounds like a family member, colleague, or supervisor.
A caller might claim to be stranded, facing an emergency, or unable to access a bank account. In a business setting, a supposed manager might urgently request a transfer to a new account.
These situations are designed to make the recipient act emotionally rather than investigate.
If someone asks for urgent payment, end the conversation and contact the person through a number or communication channel you already trust. A familiar voice should never replace independent verification.
3. Fake AI-Powered Investment Platforms
Some fraudulent platforms advertise automated systems that supposedly analyze markets, predict price movements, or generate consistent profits.
They may display dashboards, charts, transaction histories, and account balances that appear professional. After a small initial deposit, a victim might even be shown an apparent profit to encourage a larger investment.
That displayed balance does not prove the money exists. A fraudulent platform can manufacture account figures and simulated trading activity.
Warning signs include guaranteed returns, vague explanations of how the system works, pressure to deposit more money, and difficulty withdrawing funds. A claim that a platform uses AI does not establish that its technology works, that its operators are qualified, or that customer funds are protected.
4. Fake Financial Experts and Investment Groups
Scammers sometimes approach potential victims through social media, online forums, and private messaging groups. A person posing as an experienced investor may offer tips, trading signals, or access to an exclusive investment community.
Other accounts in the group may appear to confirm the claims by sharing screenshots of profits and praising the supposed expert. These accounts and testimonials can be fabricated or coordinated.
The group may begin with free advice before directing members to a particular brokerage, cryptocurrency exchange, or investment website.
Independent verification matters more than popularity inside a group. Check who operates the platform, whether the relevant professionals and firms are registered where required, and whether the proposed investment can be independently confirmed.
5. Personalized Messages and Impersonation
AI can help criminals write polished messages, adapt their language, and generate large numbers of customized communications. A message may mention a person's job, interests, recent purchases, or financial ambitions to make the sender appear familiar.
Scammers may also imitate customer-support representatives, bank employees, tax officials, or investment advisers.
A professional tone, accurate personal details, and correct spelling do not prove that a message is genuine. Treat unexpected requests for payments, passwords, verification codes, or account access with caution, even when the sender appears knowledgeable.
Warning Signs of an AI Investment Scam
No single clue identifies every scam. Some legitimate businesses have poor websites, while sophisticated fraudsters can produce convincing ones. The strongest approach is to evaluate the offer, the people behind it, and the way they expect you to pay.
Guaranteed or Unrealistic Returns
Promises of guaranteed profits, unusually high returns with little risk, or a trading system that supposedly cannot lose are major red flags.
All investments carry risk, although the type and level of risk vary. Stocks can fall, bonds can default, and cryptocurrency prices can fluctuate sharply. No claim about artificial intelligence removes those risks.
Be especially skeptical when a promoter promises consistent daily or weekly profits without providing independently verifiable evidence.
Pressure to Act Immediately
Fraudsters may claim that an offer expires within minutes, that only a few places remain, or that a special opportunity is available only to selected investors.
The objective is to prevent careful research. A legitimate investment should withstand reasonable questions and independent checks.
Do not transfer money because someone says you will miss out if you wait.
Requests for Cryptocurrency or Unusual Payments
Some scams insist on payment through cryptocurrency, wire transfers, gift cards, payment applications, or other methods that may be difficult to reverse.
Cryptocurrency itself is not proof of fraud, and legitimate businesses may use different payment methods. The concern is a combination of unusual payment demands, a lack of transparency, and pressure to act quickly.
Never send funds to a wallet or account merely because a supposed adviser says it is necessary to activate your investment or unlock profits.
Unverified Registration and Company Details
A website may display a business registration number, a professional-looking certificate, or the logo of a recognized regulator. Criminals can copy legitimate details or invent credentials.
Independently search the relevant regulator's official database. Confirm the legal name of the firm, the identity of the professionals involved, and whether they are authorized to offer the specific service being promoted.
In the United States, Investor.gov provides tools and educational resources for checking investment professionals and understanding investment fraud risks.
Problems With Withdrawals
A particularly serious warning sign appears when a platform refuses to release your money unless you pay another fee, tax, deposit, or verification charge.
A fraudulent service may invent a withdrawal problem after displaying substantial profits. It might demand additional funds to unlock the account or insist that a payment must be made in cryptocurrency.
Do not assume that paying another charge will release your existing balance. Stop sending money and seek advice from your financial institution and the appropriate authorities.
How to Verify an Investment Before Sending Money
A few deliberate checks can help prevent an expensive mistake. None offers an absolute guarantee, but together they make it harder for a fraudulent promoter to rely on appearances alone.
Research the Company Independently
Start by identifying the company's legal name, physical business address, management, and the exact financial product being offered.
Search the company name alongside terms such as "scam," "fraud," "complaint," and "withdrawal problem." Look beyond testimonials on the company's own website. Search results can also be manipulated, so treat online reviews as clues rather than conclusive proof.
Use official regulator databases to investigate registration where applicable. For U.S. securities-related services, begin with resources from the Securities and Exchange Commission (SEC), FINRA, and Investor.gov. Depending on the product, other regulators may be relevant.
Remember that registration is not a guarantee of profits or a recommendation to invest. It is one part of due diligence.
Verify Endorsements and Financial Claims
If an advertisement features a celebrity, executive, or financial expert, look for the recommendation on an independently verified official channel.
Contact the company through contact details obtained separately from the advertisement. Ask for documentation explaining the investment, its risks, fees, and withdrawal procedures.
Do not rely on a screenshot of an account balance or a video of someone claiming to have earned a fortune. Such material can be fabricated, and even genuine testimonials do not establish that an investment is suitable for you.
Test the Explanation Behind the Investment
Ask how the investment generates returns, what assets it holds, who manages the funds, and what could cause you to lose money.
For an AI trading product, ask what the software actually does, how its performance is measured, and whether the results have been independently audited. Request clear information about fees, custody of funds, and the legal entity responsible for the service.
A promoter who refuses to explain basic details, dismisses reasonable questions, or claims that the strategy is too secret to discuss may be trying to discourage scrutiny.
You do not need to understand every technical detail of a legitimate investment, but you should be able to understand the essential risks and how the product operates.
Make a Small Test Deposit? Think Carefully
Some consumers assume that making a small initial deposit is a safe way to test a platform. That approach can be misleading.
A fraudulent platform may permit a small withdrawal to build trust before encouraging much larger deposits. A successful first transaction does not prove that the service is legitimate.
Verify the company and the investment before sending any amount. Never use money needed for rent, food, bills, emergency savings, or other essential expenses to experiment with an unverified opportunity.
Protect Your Digital and Financial Information
Never share your online banking password, one-time verification code, recovery phrase, or private cryptocurrency keys with someone who contacts you unexpectedly.
Avoid installing remote-access software at the request of an unsolicited caller claiming to be from your bank or an investment company. Do not log in to financial accounts through links in unexpected messages.
Use unique passwords and multifactor authentication where available. Keep devices and applications updated, and review account notifications for unfamiliar activity.
What to Do if You Have Already Lost Money
Realizing that an investment opportunity may be fraudulent can be frightening, particularly if the amount involved is substantial. Acting quickly may help limit additional losses, although recovering money is never guaranteed.
1. Stop Sending Money
Do not pay further deposits, invented taxes, account-unlocking charges, or recovery fees demanded by the suspected scammer.
Avoid arguing with the person or accepting new promises designed to persuade you to continue. Preserve your evidence and focus on protecting what remains.
2. Contact Your Bank or Payment Provider Immediately
If you paid through a bank transfer, debit card, credit card, payment application, or cryptocurrency exchange, contact the relevant institution through its official website or telephone number.
Explain that you suspect fraud and provide the transaction details. Ask whether the payment can be stopped, recalled, disputed, or otherwise investigated.
Available options depend on the payment method, transaction status, provider policies, and applicable law. A completed bank transfer or cryptocurrency transaction may be difficult to reverse, but prompt reporting is still worthwhile.
If the scammer gained access to your account, ask the institution to secure it, review recent activity, and explain any necessary steps to protect linked accounts.
3. Secure Your Accounts and Devices
Change compromised passwords from a device you believe is safe. Prioritize email and financial accounts because access to an email account can allow criminals to reset other passwords.
Enable multifactor authentication, sign out of unfamiliar sessions, and revoke suspicious applications or connected devices where possible.
If you installed remote-access software or gave someone control of your computer or phone, disconnect the device from the internet if necessary and seek trusted technical assistance. Inform your financial institution if the device was used to access banking services.
If you disclosed identity documents or sensitive personal information, monitor your accounts and consider appropriate identity-theft protections.
4. Preserve Evidence
Save messages, emails, phone numbers, website addresses, account statements, payment confirmations, transaction IDs, wallet addresses, and screenshots of the investment platform.
Record dates, the amounts transferred, the payment methods used, and any promises made by the people involved.
Do not delete the conversation simply because it is upsetting. The evidence may help your bank, payment provider, or investigators assess what happened.
5. Report the Fraud
In the United States, consumers can report suspected scams to the Federal Trade Commission at ReportFraud.ftc.gov. Investment-related concerns can also be reported through the SEC's official complaint and investor assistance resources. The FBI's Internet Crime Complaint Center, at IC3.gov, accepts reports involving online crime.
Use the genuine government website by entering its address yourself or locating it through an official government website. Do not rely on links supplied by the suspected scammer.
A report does not guarantee reimbursement or a criminal investigation, but it can provide useful information to authorities and help identify broader fraud patterns.
Beware of Investment Recovery Scams
People who have already lost money are often targeted again. Criminals may contact victims while pretending to be lawyers, recovery specialists, government investigators, cryptocurrency tracing experts, or representatives of a fund that supposedly holds recovered assets.
They may claim that the original money has been located and can be returned after the victim pays an advance fee.
Be extremely cautious of anyone guaranteeing recovery, demanding cryptocurrency to release funds, or claiming to represent law enforcement through social media or private messaging.
The FBI has specifically warned about scammers impersonating the Internet Crime Complaint Center and using AI-generated videos and imitation websites to target people who have already reported fraud.
A legitimate government agency will not require you to pay a scammer's requested fee through an unofficial channel to obtain access to your complaint. Verify any purported investigator or recovery service independently before sharing personal or financial information.
If someone contacts you after a loss, do not assume the person is trustworthy simply because they know details of your case. Those details may have been obtained from public posts, leaked information, or the original scam.
Can Banks and Financial Apps Protect You From AI Scams?
Financial institutions use security measures such as transaction monitoring, identity verification, fraud alerts, and suspicious-activity detection. Some may also use machine-learning systems to identify unusual patterns.
These protections can help, but they cannot prevent every scam. A payment authorized by a deceived customer may look different from a transaction made by someone who has had an account taken over.
For that reason, consumers should treat bank security as one layer of protection rather than a substitute for verifying the recipient.
Before approving a transfer, double-check the recipient's details and the reason for payment. If a caller says your existing account is unsafe and instructs you to move your money to a "secure" account, contact your bank independently before doing anything.
A legitimate institution should not require you to bypass normal security procedures because a caller claims there is an emergency.
Are AI Trading Tools Always Scams?
No. Artificial intelligence can be used legitimately in financial research, data analysis, customer service, and automated trading. The important distinction is between the technology itself and the claims made by the people selling it.
A genuine financial tool should explain its purpose, costs, limitations, and risks. Its marketing should not depend on guaranteed profits or claims that it can eliminate investment risk.
Consumers should also distinguish between software that helps analyze information and a regulated financial service that manages assets or provides investment advice. The legal and regulatory requirements may differ according to the service, product, and jurisdiction.
Even a legitimate algorithm can perform poorly, rely on flawed assumptions, or lose money when market conditions change. Historical performance does not guarantee future results.
Treat AI as a tool, not a promise of wealth. Evaluate the underlying investment just as carefully as you would if the product did not mention artificial intelligence at all.
Building a Safer Financial Routine in 2026
Protecting your money does not require becoming a cybersecurity expert. A consistent set of habits can make you less vulnerable to common fraud techniques.
Verify unexpected requests independently. If a family member, colleague, bank employee, or adviser asks for money, contact that person through a trusted channel before acting.
Slow down financial decisions. Avoid making investments while frightened, excited, embarrassed, or under pressure. A legitimate opportunity should allow time for reasonable research.
Keep financial information private. Avoid sharing account details, verification codes, identity documents, or investment balances with unverified contacts.
Use official sources. Research investment professionals, review regulatory warnings, and access financial institutions through verified websites or applications.
Discuss unusual requests with someone you trust. A second opinion can help you notice inconsistencies when a persuasive message makes a decision feel urgent.
Review accounts regularly. Check transaction histories, account alerts, and security settings. Report unfamiliar transactions promptly.
Question extraordinary claims. A celebrity video, a professional-looking dashboard, a group full of enthusiastic investors, or an AI-powered label is not independent proof that an opportunity is genuine.
These habits are useful even when no artificial intelligence is involved. Many scams combine traditional manipulation with new technology, so basic financial caution remains essential.
Conclusions
AI financial scams are becoming more convincing because criminals can use technology to imitate trusted people, produce professional-looking investment promotions, and personalize their messages at scale. Deepfake videos, cloned voices, fake trading platforms, and fabricated investment communities can all create the appearance of legitimacy without providing genuine financial value.
The most effective defense is independent verification. Research the company, confirm relevant registrations, question promises of unusually high returns, and never allow an urgent message to replace careful decision-making. Protect your passwords and verification codes, and contact financial institutions through official channels when something seems wrong.
If you suspect a scam, stop sending money, notify your payment provider, secure affected accounts, preserve evidence, and report the incident to the appropriate authorities. Be especially cautious of anyone who promises to recover your losses in exchange for an upfront payment.
Artificial intelligence can support legitimate financial services, but it cannot make a risky investment risk-free or turn an unverified promoter into a trustworthy adviser. In 2026, protecting your money means looking beyond appearances, checking the evidence, and making financial decisions at your own pace.
Official resources for further guidance
- Federal Trade Commission: Investment Scams
- SEC Investor.gov: Artificial Intelligence (AI) and Investment Fraud
- FBI Internet Crime Complaint Center: Criminals Use Generative Artificial Intelligence to Facilitate Financial Fraud
- FBI Internet Crime Complaint Center: Official Website
- Federal Trade Commission: Report Fraud