

Your Home Insurance Was Renewed — So Why Is Your Mortgage Payment Suddenly Higher?
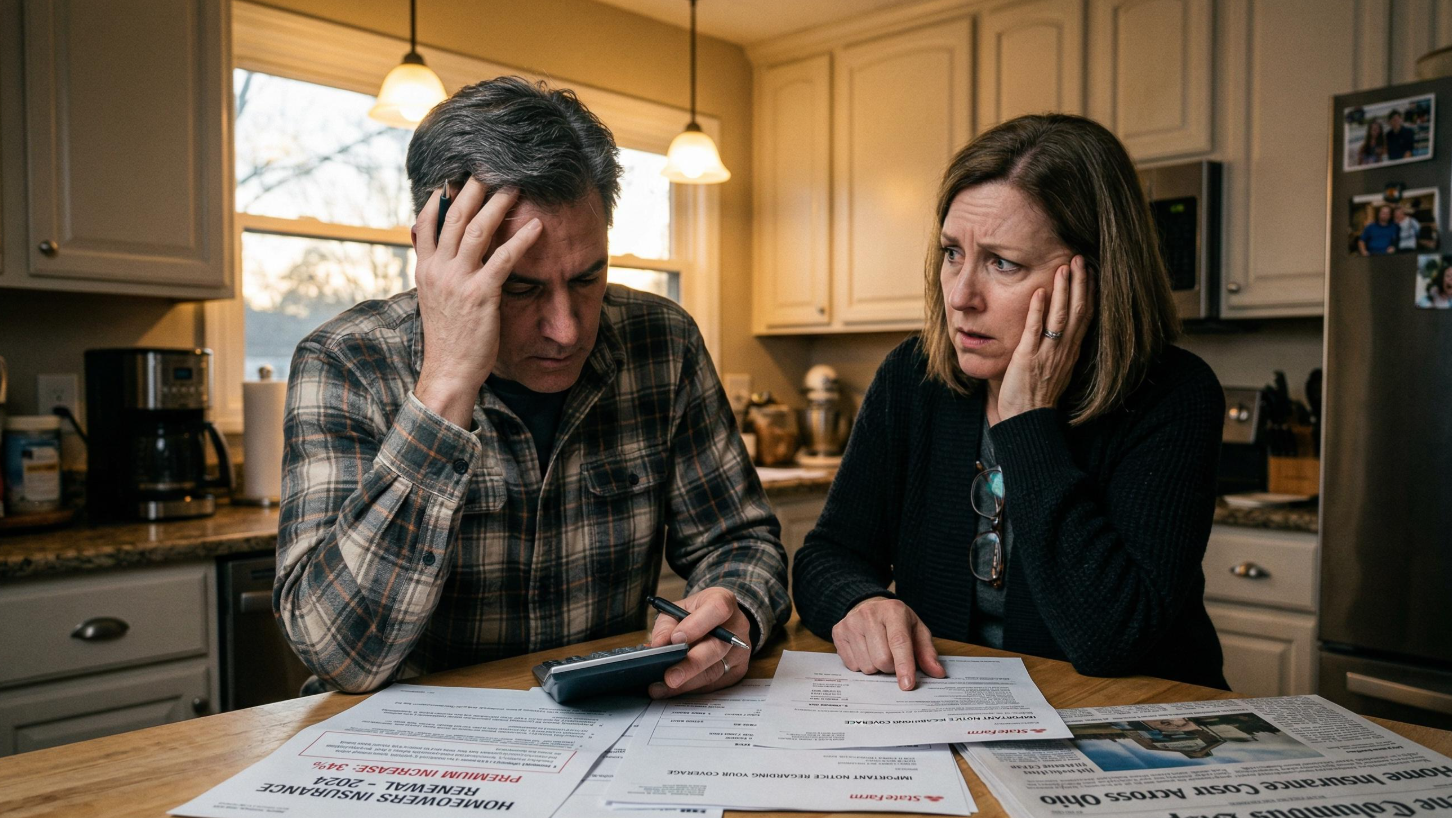
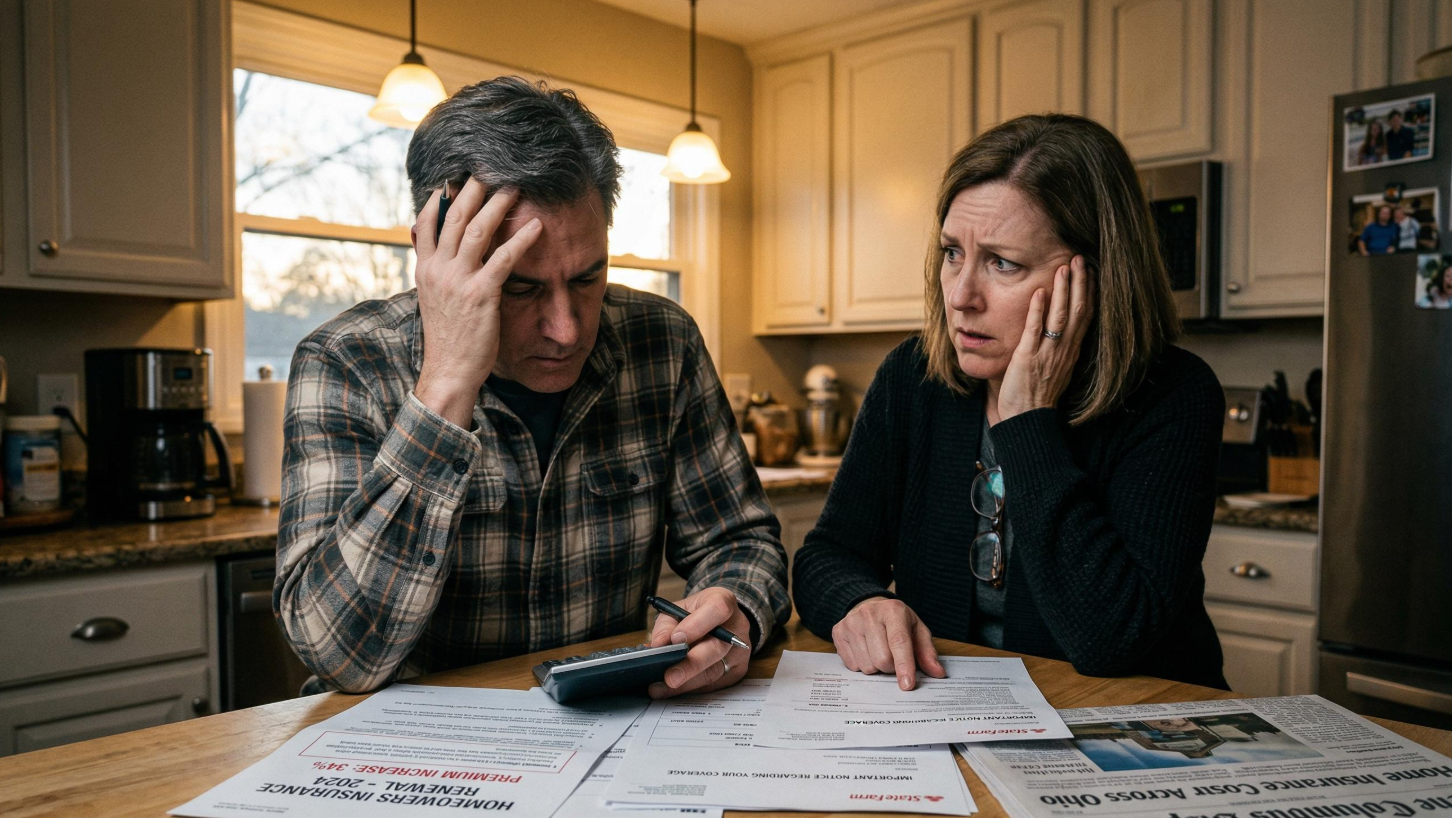
Imagine checking your mortgage statement after years of making payments on time. Your interest rate has not changed, you have not refinanced, and you have not borrowed any additional money. Yet your monthly mortgage payment has suddenly increased by $150, $250, or even more.
For many U.S. homeowners, the explanation is not a change to the mortgage loan itself. It is an escrow shortage.
An escrow account is designed to make homeownership easier by collecting money each month for expenses such as property taxes and homeowners insurance. Your mortgage servicer holds that money and pays those bills when they come due. The system can simplify budgeting, but it can also create an unpleasant surprise when insurance premiums or property taxes rise faster than expected.
The result can be a higher monthly payment, a notice demanding repayment of an escrow shortage, or both.
The confusing part is that your mortgage may have a fixed interest rate while your total monthly payment still changes. A fixed rate generally protects the principal-and-interest portion of your payment, not every expense associated with owning the property.
Understanding why your payment increased, how the escrow calculation works, and what options you have can help you avoid unnecessary financial stress. More importantly, it can help you identify errors before you pay more than you owe.
Why Did My Mortgage Payment Increase After Insurance Renewal?
Your monthly mortgage payment may include several separate costs:
- Principal: The portion that reduces the amount you borrowed.
- Interest: The cost of borrowing money.
- Property taxes: Taxes charged by your local government.
- Homeowners insurance: Coverage that protects your property against covered losses.
- Other applicable costs: These may include mortgage insurance, flood insurance, or certain property-related assessments.
When you have an escrow account, your mortgage servicer collects money for eligible property expenses along with your regular loan payment.
Suppose your principal-and-interest payment is $1,600 per month. Your servicer also collects $500 for property taxes and $200 for homeowners insurance. Your total monthly payment is $2,300.
If your homeowners insurance premium increases significantly at renewal, the insurance portion of your escrow payment may need to rise. If your property taxes also increase, the adjustment can be larger.
The Consumer Financial Protection Bureau explains that property taxes and insurance premiums can change from year to year, affecting escrow contributions and the total monthly mortgage payment. https://www.consumerfinance.gov/ask-cfpb/what-is-an-escrow-or-impound-account-en-140/
But there is another complication: your servicer may discover that your escrow account already has insufficient funds to cover expenses paid during the previous year.
That creates two separate financial pressures:
- Your monthly payment must increase to cover the new, higher expected bills.
- Your payment may also increase temporarily to repay the previous escrow shortage.
These two adjustments can arrive together, making the increase look much worse than the insurance renewal alone would suggest.
What Is an Escrow Shortage?
An escrow shortage occurs when the balance in your mortgage escrow account falls below the amount required under the servicer's escrow analysis.
Your servicer estimates how much money must be available throughout the year to pay property taxes, insurance premiums, and other eligible expenses. It compares that requirement with the money already in the account and the deposits expected from your monthly payments.
If the available balance is insufficient, the annual analysis may identify a shortage.
A shortage does not automatically mean you missed a mortgage payment. It can happen even when you have paid your mortgage on time every month.
For example, your servicer may have collected $2,400 over the year for homeowners insurance based on an earlier premium estimate. When the actual renewal bill arrives, the insurer charges $3,300. The account must cover the additional $900, assuming those figures accurately represent the amounts collected and paid.
If other escrow expenses also increase, the difference can grow.
An escrow shortage is different from an escrow deficiency. Under federal mortgage-servicing rules, a shortage generally describes a balance below the target amount identified in the analysis. A deficiency refers to a negative escrow balance. The distinction can affect how the servicer handles repayment.
You should therefore read the terminology in your escrow statement rather than assuming that every negative-looking figure means the same thing.
The Two-Part Reason Your Payment Can Jump
One of the most important things to understand is that an escrow-related mortgage increase may contain two different adjustments.
1. Your future expenses have become more expensive
Your servicer must collect enough money to pay the next round of property taxes and insurance bills.
If your annual homeowners insurance premium rises from $2,400 to $3,600, the annual cost has increased by $1,200. Spread across 12 months, that represents an additional $100 per month in insurance funding.
If property taxes rise by another $600 per year, that adds approximately $50 per month.
Together, these higher recurring expenses can increase the amount needed for future escrow deposits by approximately $150 per month, before accounting for any other adjustments.
2. Your servicer is recovering money from the previous year
Now imagine the escrow account also has a $1,800 shortage.
If your servicer spreads that amount over 12 months, the repayment component would be $150 per month.
Your monthly payment could therefore increase by approximately $300: $150 to cover higher ongoing expenses and $150 to repay the shortage.
This example is simplified. Your actual payment depends on your escrow analysis, projected bills, account balance, permitted escrow cushion, loan terms, and the repayment method used by your servicer.
The critical point is that the shortage repayment is generally temporary, while the higher insurance or tax expense may continue into future years.
Once the shortage is fully repaid, the temporary repayment component should end under the applicable schedule. However, your monthly payment may remain higher than it was before because the underlying property expenses have increased.
That distinction can help you make a more realistic household budget.
How Rising Homeowners Insurance Premiums Affect Your Mortgage
Homeowners insurance is often a significant and sometimes unpredictable cost of owning a property.
Insurers may change premiums at renewal because of factors such as rebuilding costs, the property's characteristics, claims history, coverage limits, deductibles, and local risk conditions. The amount can also vary when an insurer changes its pricing or underwriting practices.
A renewal notice does not necessarily mean that your mortgage lender has changed anything. The insurance company may simply be charging more to continue the coverage.
If your premium is paid through escrow, the higher bill eventually affects the amount your mortgage servicer needs to collect.
Consider a homeowner whose annual premium increases from $1,800 to $3,000. The annual increase is $1,200, equivalent to $100 per month when spread across a full year.
If the servicer had been collecting money based on the old premium, the escrow account may not have enough funds when the new bill arrives. The homeowner can then face both an increased monthly contribution and a shortage-repayment amount.
Why shopping for insurance can matter
You may be able to reduce your insurance expense by comparing policies from different insurers. But the cheapest quote is not automatically the best policy.
Before switching, compare:
- Dwelling coverage and estimated rebuilding costs.
- Personal property and liability coverage.
- Deductibles, including separate wind, hail, or hurricane deductibles where applicable.
- Exclusions and coverage restrictions.
- Discounts and eligibility requirements.
- The insurer's financial strength and claims service.
- Whether your mortgage servicer needs updated proof of coverage.
Avoid reducing coverage so aggressively that a major loss could leave you unable to repair or rebuild your home.
If you change insurers, make sure the new policy begins before the old policy ends. Send the updated declarations page and any required information to your mortgage servicer, and confirm that the new policy has been recorded correctly.
If your servicer has already paid the old premium or scheduled a payment that cannot be canceled, ask how that transaction will be reflected in your escrow account.
You can learn more about homeowners insurance requirements through the Consumer Financial Protection Bureau's guide: https://www.consumerfinance.gov/ask-cfpb/what-is-homeowners-insurance-why-is-homeowners-insurance-required-en-162/.
Property Taxes Can Make the Problem Even Worse
Insurance is only one possible cause of a mortgage payment increase. Property taxes can produce a similar effect.
Your local government may reassess the taxable value of your home, change tax rates, or adjust exemptions. Depending on local rules, a new assessment or the expiration of a tax benefit can increase your annual tax bill.
Suppose your property taxes increase from $4,800 to $6,000 per year. That is an additional $1,200 annually, or $100 per month when averaged across the year.
If insurance also becomes more expensive, your escrow requirement can rise substantially.
A homeowner who experiences both increases might see the future monthly escrow contribution rise by $200 before any shortage repayment is added.
Check whether your property tax bill is correct
Do not automatically assume that a higher tax bill is accurate.
Compare your latest bill with the previous year's statement. Check the assessed value, tax rate, exemptions, and any special assessments. If you recently purchased the property, pay particular attention to whether the previous owner's tax treatment or exemptions changed after the sale.
If the assessed value appears incorrect, investigate the appeal process and deadlines in your jurisdiction. Property tax appeal procedures vary by state and locality, and missing a filing deadline may limit your options.
You should also check whether you qualify for homeowner exemptions, homestead benefits, senior exemptions, or other local tax relief programs. Eligibility differs significantly by location.
Remember that a successful future appeal or exemption may reduce a later tax bill, but it does not automatically erase a shortage already calculated from prior payments. Ask your servicer how any corrected tax amount would affect the escrow account and future payment schedule.
How to Read Your Annual Escrow Analysis
When your mortgage payment changes, the annual escrow analysis is one of the most useful documents to review.
Your mortgage servicer generally conducts an escrow analysis to estimate upcoming expenses, determine required monthly deposits, and identify whether the account has a surplus, shortage, or deficiency. Federal rules govern important aspects of these calculations and the information included in escrow statements.
Instead of focusing only on the new monthly payment, look for the following details.
1. Your previous monthly escrow contribution
Find the amount that was collected each month for property taxes, insurance, and other escrowed expenses.
Compare it with the new monthly contribution. The difference gives you an initial indication of how much more your servicer expects to collect for future bills.
2. The actual property tax and insurance disbursements
Review the amounts paid from the account during the previous escrow year.
Check whether the servicer paid the expected bills, whether the figures match your tax and insurance documents, and whether any payments were duplicated or unexpectedly high.
3. The projected expenses for the upcoming year
The statement should explain the expenses used to calculate your new payment.
Compare the projected homeowners insurance premium with your renewal documents. Compare the property tax estimate with the latest tax bill or available assessment.
If the projections appear inaccurate, ask the servicer to explain the source of its figures and whether a corrected analysis is appropriate.
4. The shortage or deficiency amount
Look for the specific amount identified as a shortage or deficiency. Do not confuse that figure with the total amount of your annual taxes and insurance.
Ask how the balance was calculated and whether the servicer has included any advance payments, refunds, adjustments, or other account transactions.
5. The repayment schedule
If the statement includes shortage repayment, identify the amount that will be collected each month and the period over which it will be repaid.
This matters because the temporary repayment amount can make your payment substantially higher than the ongoing escrow requirement.
6. Your new total monthly payment
Finally, compare the old and new payment breakdowns. Separate principal and interest from escrow and other charges.
This makes it easier to determine whether the increase comes from property expenses, shortage repayment, an adjustable interest rate, mortgage insurance, fees, or some combination of factors.
The CFPB's mortgage-servicing guidance explains how escrow analyses and shortage calculations work: https://www.consumerfinance.gov/compliance/compliance-resources/mortgage-resources/mortserv/mortgage-servicing-faqs/.
Can You Pay an Escrow Shortage in Full or Monthly?
Your repayment options depend on the applicable federal rules, the size of the shortage, your loan, and your servicer's procedures.
Under the federal escrow rules in Regulation X, a servicer generally has specific options when an annual escrow analysis identifies a shortage. For a shortage below one month's escrow payment, the rules permit certain approaches, including requiring repayment within 30 days or spreading repayment over at least 12 months. For a shortage equal to or greater than one month's escrow payment, the permitted approaches differ.
These rules matter because a servicer cannot necessarily offer or require every repayment method in every situation. Review the explanation on your statement and ask the servicer to clarify which rules apply to your account.
The governing regulation is available from the CFPB: https://www.consumerfinance.gov/rules-policy/regulations/1024/17/.
Option 1: Spread the shortage across monthly payments
Monthly repayment can preserve your savings and reduce the immediate financial burden.
Suppose your shortage is $1,200 and the repayment period is 12 months. The shortage component would be $100 per month, in addition to the contribution needed for future taxes and insurance.
The advantage is that you do not have to use a large amount of cash at once. The disadvantage is that your monthly payment remains higher during the repayment period.
Option 2: Make a voluntary lump-sum payment when permitted
Paying a shortage upfront may reduce the temporary repayment component of your monthly payment if your servicer accepts the payment and applies it correctly.
However, do not assume that paying the shortage will return your mortgage payment to its previous amount. If your insurance premium or property taxes have increased, the ongoing escrow contribution may still be higher.
Before paying, ask the servicer to confirm the amount required, the payment instructions, how the funds will be applied, and whether it will issue an updated payment calculation.
Also, do not assume a lump-sum option is available as a required or standard choice under every escrow-shortage scenario. The federal rules distinguish between shortages of different sizes and between required repayment methods and voluntary payments.
Which option is better?
There is no universal answer.
If paying upfront would drain your emergency fund or force you to rely on high-interest credit cards, preserving cash may be more important than lowering the temporary monthly payment.
If you have sufficient savings after accounting for emergency expenses and other upcoming bills, a voluntary lump-sum payment may be worth considering when accepted by the servicer.
Compare the effect on your budget rather than focusing only on the amount of the monthly payment. Your goal should be to keep the mortgage affordable without leaving yourself financially vulnerable.
What If You Cannot Afford the New Mortgage Payment?
A sudden increase can be especially difficult for homeowners whose income has not increased at the same pace as insurance and property expenses.
The worst response is to ignore the notice and hope the payment returns to normal.
Instead, contact your mortgage servicer as soon as possible. Explain that the escrow adjustment has made the payment difficult to afford and ask what options may be available.
Your loan terms, investor requirements, account status, and applicable rules will determine what the servicer can offer. There is no guarantee that it will reduce the payment, extend repayment, or waive any amount, but early communication gives you more time to understand your choices.
Ask for a payment breakdown
Request a clear explanation of how much of the increase reflects higher future expenses and how much reflects repayment of a previous shortage.
If the shortage amount is incorrect, explain the discrepancy and provide supporting documents. If the calculation is accurate but unaffordable, ask about the repayment arrangement that applies to your loan.
Ask whether the analysis can be reviewed
If you believe the servicer used the wrong insurance premium, an outdated tax bill, or an incorrect escrow balance, request a review.
Provide your latest insurance declarations page, premium invoice, property tax bill, and any relevant proof of payments or refunds.
Do not assume that an estimate will automatically update when you switch insurers or receive a corrected tax bill. Confirm that the servicer has the correct information.
Protect your essential cash reserves
Before making a large payment, consider whether you need that money for utilities, food, transportation, medical costs, repairs, or other essential expenses.
A lump-sum escrow payment may reduce the temporary shortage-repayment amount, but using all your savings can create another financial emergency.
If you are struggling with the mortgage itself, ask about the servicer's home-retention or loss-mitigation department. Depending on the circumstances, it may explain available assistance or direct you to an appropriate housing counselor.
Avoid high-cost borrowing as a quick fix
Using a high-interest credit card or personal loan to cover an escrow shortage can trade one problem for another. You could end up paying interest on the borrowed amount while still facing a higher mortgage payment.
Before borrowing, explore the servicer's repayment rules, review your budget, and seek reputable housing or financial counseling where appropriate.
What If Your Mortgage Servicer Made a Mistake?
Not every payment increase is correct.
An escrow analysis can be affected by outdated estimates, inaccurate tax information, insurance changes, misapplied payments, or servicing errors. You should investigate a substantial increase that does not match your actual expenses.
Start by comparing the escrow statement with your own records.
Check whether:
- Your insurance premium matches the amount shown in the analysis.
- Your property tax estimate reflects the correct property and tax period.
- The servicer paid the right insurer or taxing authority.
- A refund, canceled policy, or replacement policy was recorded correctly.
- The escrow balance includes the payments you actually made.
- The shortage repayment amount matches the stated schedule.
If you cannot resolve the issue through a phone call, consider sending a written notice of error or a written request for information using the address and procedure designated by your servicer for those requests. Keep copies of your documents and proof of delivery.
The CFPB advises homeowners who believe their mortgage payment changed incorrectly to contact the servicer, request an explanation or corrected statement, and document the interaction. If the issue remains unresolved, a formal notice of error or information request may be appropriate.
You can also submit a complaint to the CFPB if you have a mortgage-servicing problem that the company has not resolved. The agency's consumer guidance is available at https://www.consumerfinance.gov/ask-cfpb/why-did-my-monthly-mortgage-payment-go-up-or-change-en-213/.
Continue to follow your mortgage payment obligations while the issue is being reviewed. Do not simply reduce or skip a payment based on your own calculation without confirming the applicable requirements with the servicer or a qualified adviser.
Should You Refinance to Lower the Payment?
When a mortgage payment jumps, refinancing may look like an obvious solution. In many escrow-shortage cases, however, refinancing does not address the underlying problem.
A refinance replaces your existing mortgage with a new loan. It may change your interest rate, repayment term, closing costs, and monthly principal-and-interest payment.
But it does not automatically make your property taxes or homeowners insurance cheaper. If the new loan includes an escrow account, the servicer will still need to collect enough money for future property expenses. A new escrow account may also require an initial deposit at closing.
Before refinancing, compare the full costs of the new loan with the potential savings. Consider closing costs, the length of time you expect to remain in the home, the new interest rate, and whether extending the repayment term would increase the total interest you pay.
If your existing mortgage has a favorable fixed rate, replacing it solely to address a temporary escrow repayment may be an expensive mistake.
You may be better served by checking the tax and insurance estimates, correcting any servicing error, and choosing an appropriate shortage-repayment arrangement.
Refinancing deserves a closer look when the overall loan terms are unfavorable and the expected long-term savings justify the costs—not simply because an escrow adjustment arrived at an inconvenient time.
Can You Remove Escrow From Your Mortgage?
Some homeowners wonder whether they can avoid future escrow surprises by paying property taxes and insurance directly.
In certain circumstances, a lender or servicer may permit an escrow waiver. However, eligibility depends on the loan agreement, applicable law, the loan's characteristics, payment history, and investor or servicer requirements.
You should not assume that an escrow account can be removed simply because you prefer to handle the bills yourself.
If a waiver is available, consider both the advantages and the risks.
Potential advantages:
- You have more direct control over when money is set aside for property bills.
- You can choose how to organize your savings.
- You can see the bills and payments without relying entirely on the servicer's escrow administration.
Potential disadvantages:
- You must budget for large tax and insurance bills yourself.
- You may face penalties or other consequences if you miss a payment.
- Your lender may still require proof of adequate insurance.
- You could face lender-placed insurance if required coverage lapses, which may be more expensive and may provide less protection for your interests.
An escrow waiver also does not erase an existing shortage automatically. Ask your servicer whether a waiver is available and how any outstanding balance would be handled.
For many homeowners, escrow remains useful because it spreads major annual expenses across regular monthly payments. The real issue is whether the account has been calculated accurately and whether the homeowner understands how adjustments work.
How to Prepare for the Next Escrow Increase
You cannot control every insurance premium or tax assessment, but you can make a future adjustment less disruptive.
Build a home-expense reserve
If your budget allows, keep savings specifically for property taxes, insurance deductibles, repairs, and other homeownership costs.
Even if your servicer collects escrow, a separate reserve can help cover an unexpected increase or another essential repair.
Review your insurance before renewal
Do not wait until the new premium has already been paid to examine your coverage. Review renewal notices, compare suitable policies, and ask your insurer about available discounts or changes that could reduce the premium without leaving important gaps in coverage.
Read property tax notices promptly
Check assessment notices and tax bills when they arrive. If something appears wrong, investigate the relevant correction or appeal process before its deadline.
Keep your documents organized
Save your annual escrow analysis, insurance declarations pages, premium invoices, property tax bills, and mortgage statements. Having these records available makes it easier to identify a discrepancy and support a request for review.
Budget for the full housing cost
A mortgage payment is not always the complete cost of owning a home. Maintenance, utilities, repairs, insurance deductibles, homeowners association fees, and other expenses can affect your budget.
A realistic housing budget should account for these costs instead of assuming that the current monthly mortgage payment will remain unchanged forever.
The Bottom Line: A Fixed Mortgage Rate Does Not Freeze Every Housing Expense
A mortgage payment increase after an insurance renewal can feel unfair, especially when you have never missed a payment and your loan has a fixed interest rate.
But the increase may reflect higher property taxes or insurance premiums, a shortage from the previous escrow year, or both. The principal-and-interest portion of a fixed-rate mortgage can remain unchanged while the escrow portion rises.
Start by reading your annual escrow analysis and separating the increase into its individual components. Verify the insurance and tax figures, review the shortage calculation, and ask your servicer to explain anything that does not make sense.
If the shortage is accurate, compare the available repayment arrangements with your household budget. If the numbers are wrong, request a review and keep records of your communications.
Most importantly, do not assume that paying an escrow shortage in full will permanently restore your old monthly payment. The temporary shortage-repayment amount may disappear, but higher recurring property expenses can continue to affect what you owe.
The earlier you understand the reason for the increase, the easier it becomes to make a practical decision and protect your finances.